The The Aristo Phu My Hung sales policy 2026 is built on 3 core components: a construction-linked payment schedule with an initial deposit of just 20%, a bank loan programme at VCB and BIDV with a preferential interest rate of 0% and a principal grace period until handover in 2028, together with a set of exclusive benefits for pioneer customers purchasing in the first launch phase. This is the consistent policy model that Phu My Hung successfully applied at The Aurora and The Antonia, now carried forward and upgraded at The Aristo.
In addition, pioneer customers who buy early during the first launch phase enjoy 4 groups of special benefits not available in later phases: priority in choosing high-floor units with attractive orientations, early payment discounts, furniture gift packages and priority after-sales service benefits. All of these benefits disappear entirely once the project moves into the general sales phase.
Furthermore, to help buyers work out their real personal cash flow, this article includes full examples of minimum income calculations for each unit type, the amounts payable at each stage from 2026 to 2028, and a specific comparison of loan conditions between VCB and BIDV, so buyers can proactively prepare their financial documents in advance.
Below is the complete detailed information on The Aristo Phu My Hung sales policy 2026.
What Are the Main Components of The Aristo Phu My Hung Sales Policy 2026?
The Aristo Phu My Hung sales policy 2026 is a set of financial terms comprising 3 components: a construction-linked payment schedule spread gently across multiple instalments, a VCB and BIDV bank loan programme with 0% interest during the construction period, and an exclusive incentive package for pioneer customers who reserve early.
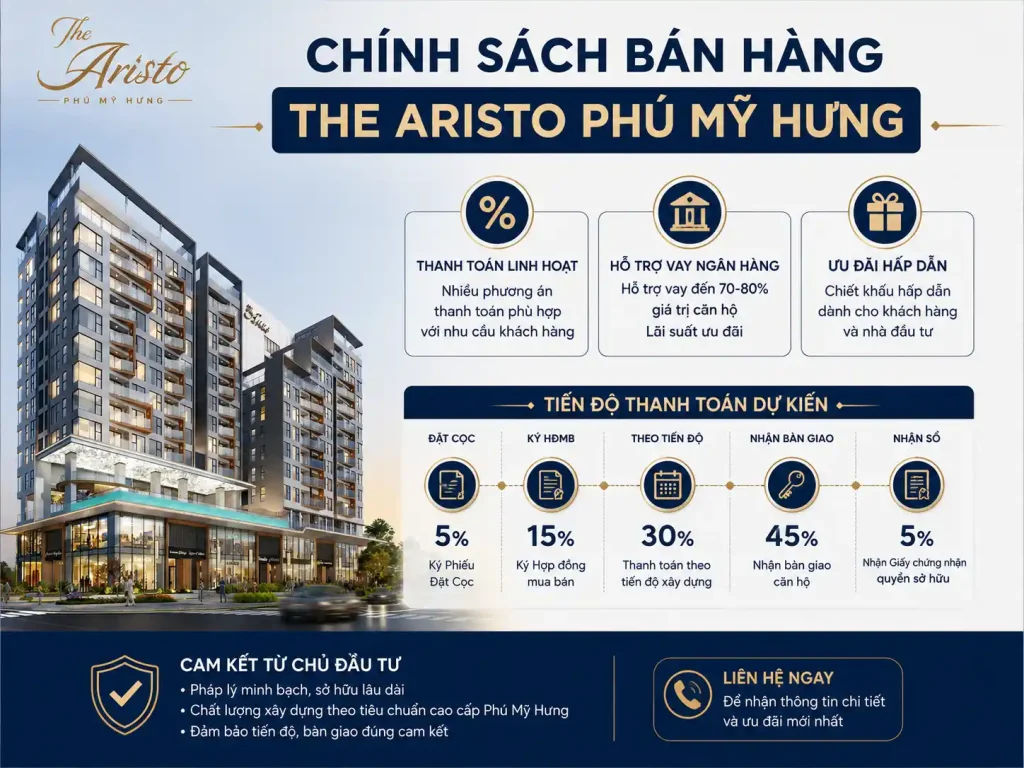
More specifically, the most critical point of The Aristo sales policy is that buyers only need to have 20% of their own funds in hand at the time of signing the sale and purchase contract. The remainder is spread lightly across multiple construction milestones or supported by a 70% loan from VCB and BIDV with a preferential 0% interest rate and a full principal grace period until handover in 2028. This is the consistent financial policy model that Phu My Hung successfully applied at The Aurora (handed over in late 2025) and The Antonia, providing a reliable reference for buyers evaluating The Aristo.
How Many Instalments Is The Aristo Phu My Hung Payment Schedule Divided Into According to Construction Progress?
The Aristo Phu My Hung payment schedule is divided into multiple small instalments linked to key construction milestones, from contract signing in late 2026 to the expected handover in 2028, with the first instalment at just 20% and subsequent instalments of 5 to 10% each.
The table below illustrates the indicative construction-linked payment schedule structure at The Aristo, based on the model applied at The Aurora and The Antonia. The official payment schedule will be announced by the Phu My Hung sales department upon contract signing:
| Payment instalment | Progress milestone | Percentage (%) | Notes |
| Phase 1 | Sale and purchase contract signing (late 2026) | 20% | Initial deposit, own funds |
| Phase 2 | Basement completion | 5-10% | According to confirmed construction milestone |
| Phase 3 | 5th floor structure completed | 5-10% | According to confirmed construction milestone |
| Phase 4 | Topping out of the building | 5-10% | According to confirmed construction milestone |
| Instalment 5 | Exterior finishing completed | 5% | According to confirmed construction milestone |
| Final phase | Handover 2028 | Final settlement of the remaining balance | Or loan disbursement from VCB/BIDV |
More importantly, throughout the 2026–2028 period, buyers using the bank loan package do not have to pay any principal or interest to VCB or BIDV. The only cash outflow during this period consists of the small construction-linked instalments, helping buyers manage their cash flow and maintain other investments in parallel.
How Much Does the 20% Deposit for The Aristo Equate To for Each Unit Type?
The 20% initial deposit upon signing the The Aristo Phu My Hung sale and purchase contract equates to between 1.2 billion and over 3.8 billion VND depending on unit type — the minimum amount of own funds buyers need to have in hand before signing.
The table below calculates the actual 20% deposit for each unit type at The Aristo, helping buyers clearly determine the initial financial capacity they need to prepare:
| Apartment type | Reference price | 20% deposit | Vay 70% (VCB/BIDV) |
| 1 bedroom (46–62m²) | 6–7 billion VND | 1.2–1.4 billion | 4.2–4.9 billion |
| 2 bedrooms (69–79m²) | 9–12 billion VND | 1.8–2.4 billion | VND 6.3–8.4 billion |
| 3-bedroom/Tophouse (102–151m²) | VND 15–19 billion | VND 3–3.8 billion | VND 10.5–13.3 billion |
| Penthouse | From VND 19 billion upwards | From VND 3.8 billion | From VND 13.3 billion |
Important note: The reference prices above are based on the price levels of PMH’s fourth-generation projects. The official price list had not been released by the developer at the time of writing. Buyers should contact the Phú Mỹ Hưng sales office to obtain the official price list for each specific unit.
On What Terms and Ratios Do VCB and BIDV Support Loans for The Aristo Purchases?
VCB and BIDV are the two state-owned commercial banks officially appointed by Phú Mỹ Hưng to provide loans for The Aristo purchases, both lending up to 70% of the apartment value at a preferential 0% interest rate during the construction period, but differing in maximum loan tenor: VCB lends for up to 35 years while BIDV lends for up to 30 years.

Specifically, both banks are financial institutions with the widest networks in Vietnam and long-standing reputations in financing high-end property purchases. PMH’s selection of VCB and BIDV as partner banks not only secures the best borrowing conditions for buyers but also provides additional assurance of the project’s legal status and financial credibility. Beyond lending, both banks also act as supervisory banks for the escrow account, protecting buyers’ payments throughout the construction period.
What Is the Maximum Percentage of The Aristo Apartment Value That VCB and BIDV Will Lend?
Both VCB and BIDV lend a maximum of 70% of the value of a The Aristo apartment, with different loan tenors: up to 35 years at VCB and up to 30 years at BIDV, giving buyers the flexibility to choose the bank that best suits their long-term financial plans.
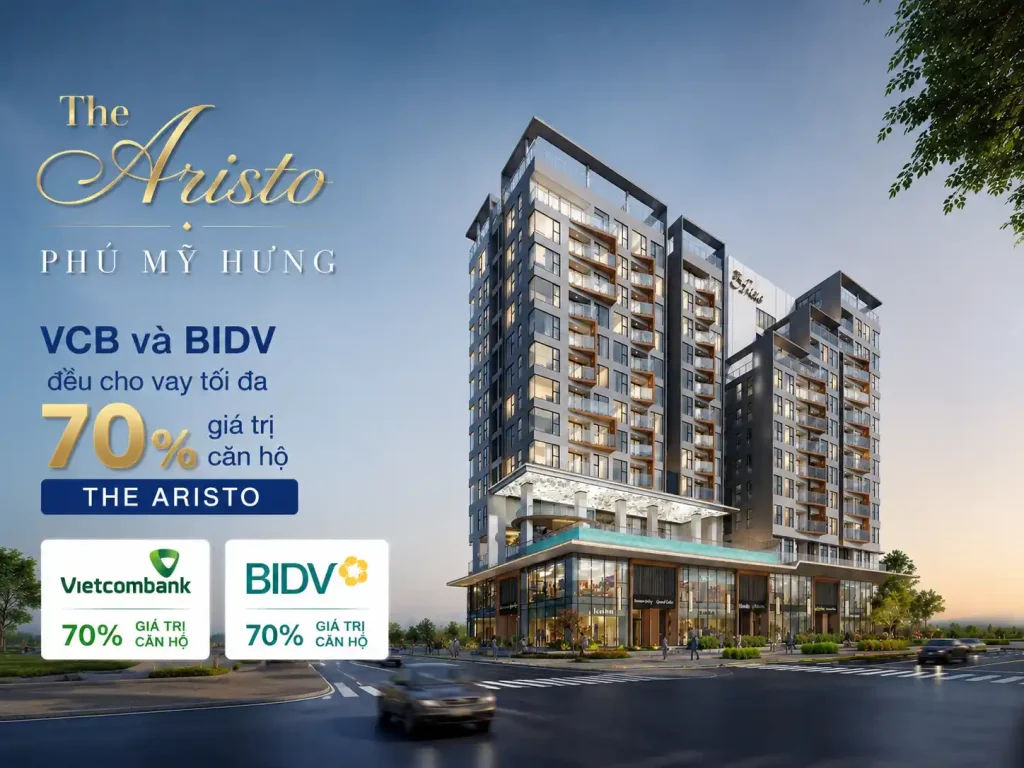
The table below summarises the main loan conditions at VCB and BIDV when purchasing a The Aristo Phú Mỹ Hưng apartment, helping buyers compare and select the most suitable bank:
| Condition | VCB (Vietcombank) | BIDV |
| Maximum loan ratio | 70% of apartment value | 70% of apartment value |
| Maximum loan term | 35 years | 30 years |
| Interest rate during construction | 0% (subsidised by the developer) | 0% (subsidised by the developer) |
| Principal grace period | Until handover in 2028 | Until handover in 2028 |
| Repayments begin | From the first month after handover | From the first month after handover |
VCB’s 35-year loan tenor is a clear advantage over BIDV’s 30 years, as a longer term reduces the monthly repayments due after handover, easing cash-flow pressure on buyers—particularly in the early years of owning the apartment. Buyers who wish to optimise their monthly cash flow after handover should prioritise VCB, or choose BIDV if they have greater repayment capacity and wish to clear the debt five years sooner.
What Does the 0% Interest Rate During The Aristo’s Construction at VCB and BIDV Mean for Buyers?
The 0% interest rate during The Aristo’s construction period means that all interest accruing on the loan from VCB or BIDV between disbursement and handover is paid on the buyer’s behalf by the developer, Phú Mỹ Hưng; buyers pay no interest whatsoever during this period.
In practice, this means the following: VCB or BIDV still charges interest normally under the loan agreement, but the interest accrued is covered directly by PMH to the bank on the buyer’s behalf. All the buyer sees is the end result: the outstanding principal does not increase throughout the 2026–2028 period. In addition, the principal grace period means the bank does not require the buyer to repay any principal during construction. The buyer only begins repaying both principal and commercial-rate interest from the first month after signing the apartment handover certificate in 2028, according to the fixed repayment schedule agreed with VCB or BIDV.
From Contract Signing Until The Aristo Handover in 2028, How Should Buyers Prepare Their Cash Flow?
From signing the contract in late 2026 until receiving the home in 2028, buyers of The Aristo only need to prepare cash flow for the lighter construction progress instalments and pay no principal or interest to the bank – a period that represents the “most financially comfortable stage” in the entire ownership lifecycle of the apartment.
Specifically, the actual year-by-year cash flow for a buyer using a bank loan package is as follows: in 2026, pay the 20% own capital upon signing the contract; during 2027, pay small progress instalments of roughly 5–10% each according to construction milestones; in 2028, take handover, settle the final instalment and begin repaying principal and interest to the bank on the fixed schedule. This cash-flow structure allows buyers to maintain other parallel investments during 2026–2028 without the pressure of double repayment obligations.
What Is the Minimum Income Required to Qualify for a VCB or BIDV Loan to Buy The Aristo?
The minimum income required to qualify for a VCB or BIDV loan to buy The Aristo ranges from around VND 65 to 130 million in net monthly income depending on unit type, based on the principle that monthly repayments must not exceed 40–50% of net income under the general rules of VCB and BIDV.
The table below calculates the actual minimum income required for each loan scenario at The Aristo, assuming a commercial interest rate of around 8% per annum after the grace period:
| Apartment type | Reference price | Vay 70% | Term (VCB) | Monthly repayment | Minimum net income |
| 1PN | 7 billion VND | 4.9 billion VND | 35 years | VND 33–36 million | VND 66–72 million/month |
| 1PN | 7 billion VND | 4.9 billion VND | 30 years (BIDV) | VND 36–40 million | VND 72–80 million/month |
| 2PN | VND 10 billion | 7 billion VND | 35 years (VCB) | VND 47–52 million | VND 94–104 million/month |
| 2PN | VND 10 billion | 7 billion VND | 30 years (BIDV) | VND 51–57 million | VND 102–114 million/month |
| 3PN | VND 15 billion | VND 10.5 billion | 35 years (VCB) | VND 71–78 million | VND 142–156 million/month |
VCB’s clear advantage of 35 years versus BIDV’s 30 years is immediately visible in the calculations: for the same VND 4.9 billion loan on a one-bedroom unit, VCB’s 35-year term saves roughly VND 3–4 million per month compared with BIDV’s 30-year term. Accumulated over the first five years after handover, this difference amounts to VND 180–240 million—enough to invest in a parallel channel. In addition, income can be combined from two co-borrowers (typically a married couple), making it easier for young, successful families to meet the required income threshold than for individual borrowers.
Do The Aristo Buyers Have to Pay Anything to the Bank During the 2026–2028 Construction Period?
No. The Aristo buyers using the VCB or BIDV loan package do not have to pay any principal or interest to the bank during the 2026–2028 construction period, because all accruing interest is covered by PMH and the principal grace period runs in full until the handover date.
This means the only cash flow buyers need to prepare during 2026–2028 is the construction-progress instalments under the contract. Only after the handover date in 2028 do buyers begin making monthly repayments according to the fixed schedule agreed with VCB or BIDV, at the commercial interest rate stated in the loan agreement. This feature allows buyers to optimise their personal cash flow for the first two years, as they face no bank repayment pressure while still paying the periodic progress instalments.
What Benefits Does the Pioneer Customer Programme for The Aristo’s First Sales Phase Include?
The pioneer customer incentives for The Aristo’s first phase comprise four main benefit groups: priority unit selection before the general launch, early-payment discounts, a furniture gift package and priority after-sales service benefits—all of which lapse entirely once the project moves into the general sales phase.
More importantly, throughout PMH’s development history, each project’s pioneering phase has always been the moment offering the best total financial and non-financial value for buyers. At The Aurora, pioneering customers received this entire package of incentives, and the best units facing the boulevard and the high floors were all reserved during this phase before the general release. The Aristo is the next project in the series and is expected to offer a similar policy, but the official policy will be announced by PMH at launch.
What Is the Priority Right to Choose the Best Units During The Aristo’s Pioneering Phase Worth?
The priority right to choose the best units during The Aristo’s pioneering phase has a real financial value of 5 to 10% of the apartment’s value, equivalent to 500 million to over 1 billion VND, since this is the price difference between a high-floor corner unit with a good facing and an ordinary unit on the same floor that pioneering customers can choose at the base price.
Specifically, when buying during the pioneering phase, buyers have the right to choose units directly according to their wishes from the entire remaining inventory. This means they can choose a corner unit on floors 10-12 with a north-east balcony facing the Nam Thong villas and the park, or a corner unit with a south-west balcony overlooking the whole of Nguyen Luong Bang Boulevard, at the base price before it is adjusted for market supply and demand. After the general release, the best units are usually gone or have moved to secondary prices 5 to 10% higher than the launch price, meaning later buyers must pay an extra 500 million to 1 billion VND for the same unit that pioneering customers bought at a lower price in the first release.
What Specific Discounts and Gifts Do Early-Booking The Aristo Customers Receive?
Customers who book early at The Aristo receive at least 3 groups of additional benefits: a fast-payment discount of 1 to 2% of the apartment’s value, a furniture gift package or shopping vouchers from PMH partners, and priority after-sales service benefits.
Specifically by benefit group: On the fast-payment discount, referencing the policy of the predecessor The Aurora, PMH applies an additional discount of 1 to 2% for customers who pay 95% of the apartment’s value early before handover, equivalent to 100 to 200 million VND on a 1-bedroom unit priced at 7 billion VND. On furniture gifts, PMH’s previous projects all included a full furniture package or furniture shopping vouchers from partners introduced by PMH, such as Mobalpa, Häfele or other premium furniture brands. On service benefits, pioneering customers are usually given priority when registering for parking spaces (supply is limited), free interior design consultation from the PMH team, and faster legal procedure support than later buyers. Important note: Specific details of discounts and gifts at The Aristo will be officially announced by the developer PMH at the project launch event. The information above is a reference drawn from the policies of predecessor projects, not an official commitment.
What Mechanism Protects The Aristo’s Progress Payments If the Project Encounters Difficulties?
Yes, The Aristo buyers’ progress payments are fully protected by an Escrow Account supervised by VCB or BIDV, ensuring that PMH may only disburse funds as each specific construction milestone is reached, and buyers have the right to request a refund if the project is not completed in line with its commitments.
This is an additional layer of financial protection entirely different from the usual mechanism at many projects on the market. The involvement of VCB and BIDV as both lending bank and escrow monitoring bank creates a two-tier control system that both protects buyers and compels PMH to maintain a strict construction schedule.
What Is an Escrow Account at The Aristo Phu My Hung and How Does It Protect Buyers?
An escrow account at The Aristo is an account managed independently by VCB or BIDV, into which all of the buyer’s progress payments are transferred, and from which PMH may only disburse funds in stages once the bank confirms that the construction milestone has been met. If PMH does not complete the project as committed, buyers have the right to request a refund from the escrow account through the bank guarantee mechanism, protecting the full amount paid against the risk of total loss. This is a mandatory standard under the Law on Real Estate Business and has been applied consistently by PMH across all its projects for more than 30 years, creating a proven foundation of trust.
How Do the Lending Policies at VCB and BIDV Differ When Buying at The Aristo?
VCB lends 70% with a maximum term of 35 years, while BIDV lends 70% with a maximum term of 30 years. Both apply a 0% interest rate during the construction period and defer principal repayment until handover, but VCB’s 35-year term helps buyers reduce their monthly repayment by 3 to 5 million VND compared with BIDV’s 30 years on the same loan. Buyers should submit applications to both banks in parallel to compare post-deferral commercial interest rates, collateral requirements and specific approval times for their individual circumstances before deciding which bank to choose. Opt for VCB if you want to optimise monthly cash flow; consider BIDV if you have a high income and want to clear the debt sooner.
If you are interested in Phú Mỹ Hưng projects, please contact Phú Mỹ Hưng Center for accurate advice and the latest information. Experienced consultant Kim Thùy is always ready to help you choose a project suited to your requirements for living or investment, while providing complete information on prices, floor plans, sales policies and legal matters.
Phumyhungcenter.com is a trusted website that supports customers throughout the process of researching and transacting Phú Mỹ Hưng projects.