The sales policy for Hồng Hạc City comprises 2 main payment methods: payment in cash according to the schedule, or a bank loan with 0% interest until handover—both allowing customers to prepare only 20% upfront to purchase the property, with the remainder supported by Vietnam’s 3 largest guarantor banks: Vietcombank, BIDV and VIB. This is the strongest financial policy currently available in the villa and townhouse segment in the Northern market.
In terms of financial incentives, Hồng Hạc City offers 4 incentives simultaneously: 0% interest during construction, interest-rate support of 3% per annum for 12 months after handover, extending payment until handover after signing the Sale and Purchase Agreement, and financing of up to 70% of the property’s value—creating the lightest possible financial burden throughout the ownership cycle, from placing a deposit to receiving the property.
In terms of benefits and commitments, Phu My Hung Development Corporation signs the Sale and Purchase Agreement directly with customers, without intermediaries; the agreement is guaranteed by 3 major banks, and handover is committed for December 2026 as scheduled. With a history of 114 projects handed over on time over 30 years, this is an evidence-based commitment, not merely a promise on paper.
Below is a complete, detailed analysis of Hồng Hạc City’s sales policy—from each payment method and financial incentive to customer benefits, eligibility conditions and application procedures—to help you choose the optimal option for your financial circumstances.
What Payment Methods Are Included in Hồng Hạc City’s Sales Policy? An Overview of the Options
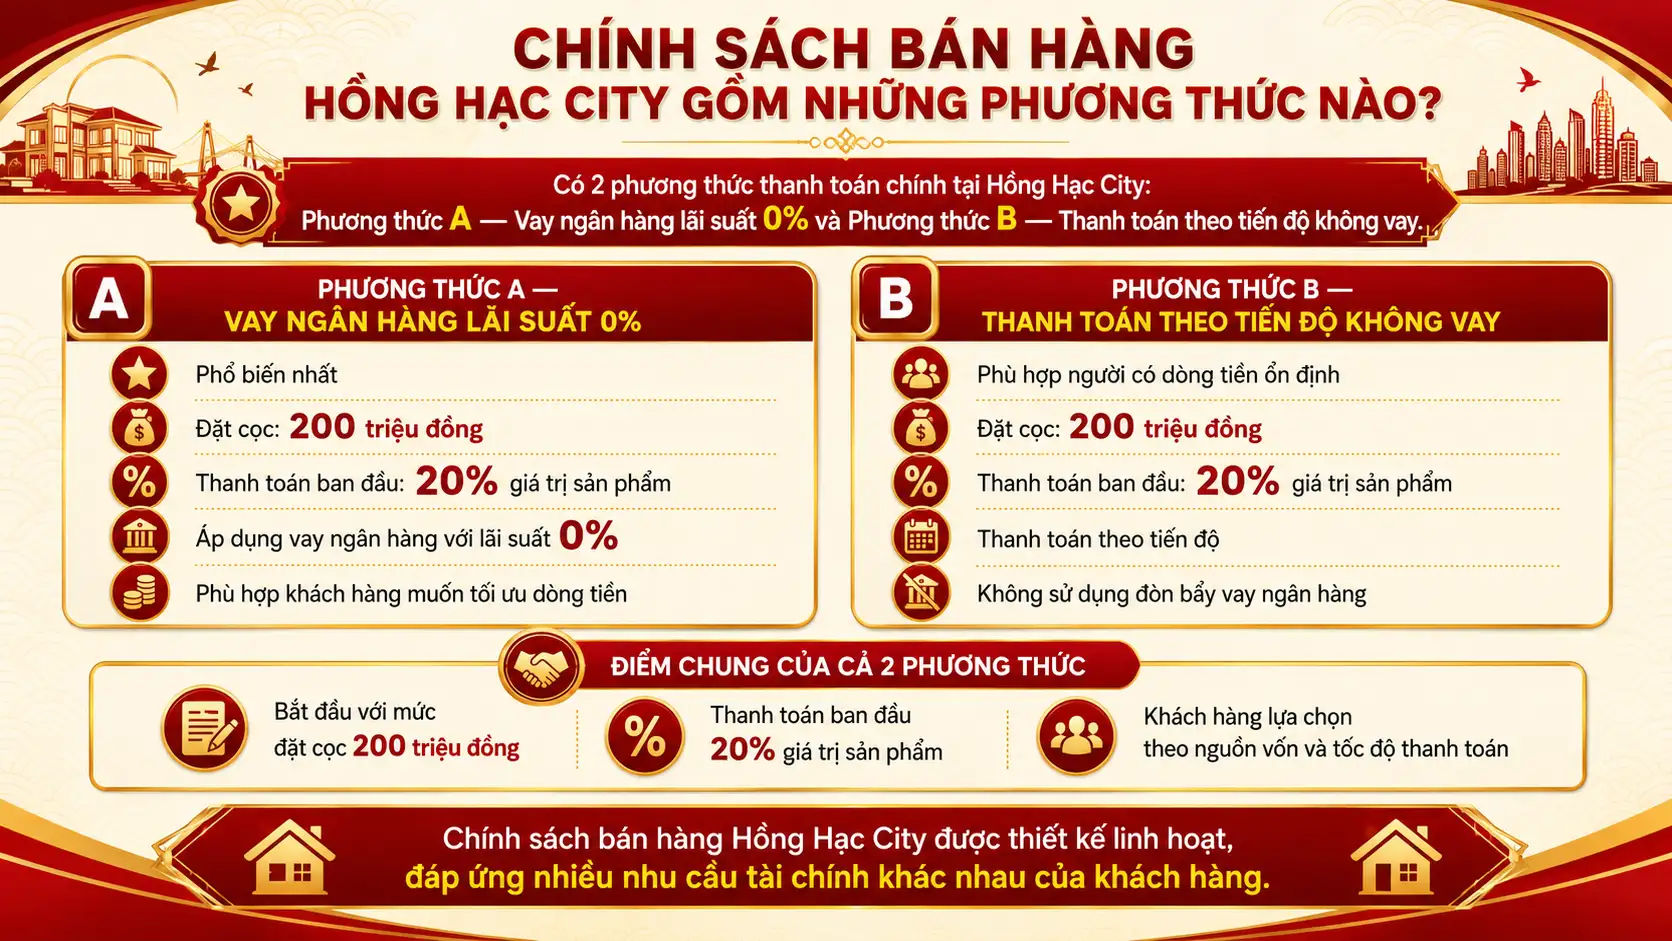
There are 2 main payment methods at Hồng Hạc City, based on funding source and payment speed: Method A — Bank financing at 0% interest (the most popular), and Method B — Payment according to the schedule without financing (suitable for those with stable cash flow). Both begin with a VND 200 million deposit and an initial payment of 20% of the property’s value.
More specifically, the table below provides an overview comparing 3 methods:
| Criteria | Method A (0% financing) | Method B (scheduled payments) | Method C (fast payment) |
|---|---|---|---|
| Initial cash required | 20% (~VND 3 billion for a VND 15 billion unit) | 20% + instalments | The full amount or >70% |
| Interest rate | 0% until handover | No interest incurred | No interest incurred |
| Cash-flow pressure | Lowest | Average | Highest initially |
| Discount | Standard | Standard | May receive an additional 1–3% |
| Suitable for | Most buyers | Those with a stable cash flow | Investors with substantial capital |
Comparison table of the 3 payment methods at Hong Hac City by the criteria of cash required, interest rate and suitability for each buyer group.
In addition, the most important common feature of all 3 methods is that every buyer signs the Sales and Purchase Agreement directly with Phu My Hung (with no intermediary), is guaranteed by 3 major banks and is offered the same property price — there is no difference in treatment between buyers who choose a loan and those who do not.
How Does the 0% Interest Bank Loan Method Work at Hong Hac City?
The 0% interest loan method at Hong Hac City is a financing package in which the bank disburses 30% of the property value in 6 instalments tied to construction progress, at 0% interest with a full principal grace period until handover (December 2026) — buyers pay no interest or principal whatsoever throughout the 17 months from signing the SPA to handover.
More specifically, the 0% loan package works in stages as follows:
Stage 1 — Buyer pays directly (20%):
- Deposit: VND 200 million
- 16 June 2025: Pay 5% (excluding VAT)
- 10 July 2025: Pay 15% + VAT to sign the SPA
- Total paid by the buyer: ~20% + VAT
Stage 2 — Bank disburses on the buyer’s behalf (30%):
- The bank disburses 30% in 6 instalments tied to construction progress
- Interest rate: 0% — no financing costs arise for the buyer
- Principal grace period: in full until handover in December 2026
- The buyer needs to provide no further cash during these 17 months
Stage 3 — Handover (45% + 5%):
- Pay 45% at handover (a further 35% may be borrowed; 10% self-funded)
- Pay the final 5% upon receiving the ownership certificate
Illustrative example for a VND 15 billion townhouse:
- Cash required in June–July 2025: ~VND 3.2 billion (20% + VAT)
- July 2025 – December 2026: the bank pays VND 4.5 billion (30%) on the buyer’s behalf; the buyer contributes nothing further
- Handover in December 2026: a further ~VND 6.75 billion (45%) required — additional borrowing is possible
- Ownership certificate: a final VND 750 million (5%)
More importantly, a distinctive feature of this 0% loan package is that the bank disburses on the buyer’s behalf in line with construction progress — rather than the buyer borrowing money and paying the developer themselves, the bank and the developer coordinate directly. This ensures the disbursed funds are used for their proper construction purpose and are not misused.
How Does the Non-Loan Progress Payment Method Work at Hong Hac City?
The non-loan progress payment method is an arrangement in which the buyer pays instalments of 3–5% every 3 months from signing the SPA until handover, without a bank loan and with no interest incurred — suitable for buyers with a stable cash flow from business or a high income who wish to minimise borrowing.
More specifically, here is a comparison of the total amount payable under the 2 methods:
The 0% loan method: the total equals the contract value + VAT, but is spread more gradually. Once the 0% period ends, it converts to a commercial interest rate — additional interest costs arise
The non-loan progress method: the total is exactly the contract value + VAT, with no loan interest, but it requires a steady cash flow every quarter
Practical conclusion: buyers with a fixed income (a high salary) or stable business cash flow typically choose the progress method to avoid bank debt. Buyers wanting to optimise cash flow and leverage financing typically choose the 0% loan package, keeping cash available for other purposes during construction.
What Financial Incentives Does Hong Hac City Offer? Are There Any Discounts?
There are 4 main financial incentives at Hong Hac City, categorised by when they apply: 0% interest during construction, 3%/year interest support after handover, extended payments until handover and early-payment discounts — all combining to create a comprehensive financial incentive package from SPA signing through to full ownership of the property.
More specifically, the 4 incentives are analysed in detail by their real-world value for a VND 15 billion townhouse:
| Incentive | Applicable period | Estimated savings (VND 15 billion property) |
|---|---|---|
| 0% interest during construction | July 2025 – December 2026 (~17 months) | ~VND 680 million (calculated at 8%/year interest on 30% = VND 4.5 billion) |
| 3%/year interest support after handover | December 2026 – December 2027 (12 months) | ~VND 300 million (on a total outstanding balance of ~VND 10 billion) |
| 18-month payment extension | From SPA signing | Cash-flow flexibility; not directly quantified |
| Early-payment discount | Depending on timing | ~VND 150–450 million (1–3%) |
Estimated real-world value of the 4 financial incentives at Hong Hac City, based on a townhouse priced at VND 15 billion — figures are for reference only.
How Does the 3%/Year Post-Handover Interest Support Policy Apply?
The policy of supporting a 3%/year interest rate after handover is an incentive whereby developer Phu My Hung covers the difference between the commercial bank interest rate and the 3%/year level during the first 12 months after the handover date (from December 2026 to December 2027) — significantly reducing the financial burden during the most critical transitional period for homebuyers.
More specifically, the practical significance of this incentive:
Suppose that after receiving the home in December 2026, the customer still has an outstanding balance of VND 10 billion at the bank at a commercial interest rate of 9%/year:
- Without support: the customer pays interest of ~VND 75 million/month (~VND 900 million/year)
- With 3%/year support: the customer only pays interest of ~VND 25 million/month (~VND 300 million/year)
- Savings: ~VND 50 million/month, ~VND 600 million over 12 months
This is no small sum — VND 600 million in savings is enough to fully furnish an entire townhouse, or to serve as a financial buffer to stabilise life during the first year in a new home.
More importantly, the first 12 months after handover are typically the period of highest spending for homebuyers: furniture, appliances, minor repairs, and moving costs. The 3%/year policy arrives at exactly the right time and in exactly the right place — easing loan interest pressure just as spending needs peak.
Is There an Early Payment Discount Policy or Special Incentive for Phase 1 Buyers?
Yes — Hồng Hạc City offers an early payment discount for customers who pay 95% of the property value before the handover date, with the discount typically ranging from 1–3% depending on timing and the developer’s decision — but more importantly, Phase 1 buyers already enjoy the largest “implicit discount”: the lowest base price across the entire 2025–2036 roadmap.
More specifically, an analysis of whether to take the early payment discount:
Option 1 — Pay 95% early, receive a 2% discount:
- For a VND 15 billion unit: save ~VND 300 million
- But you must put up an additional ~VND 10.5 billion in cash earlier than planned
- Opportunity cost: if that VND 10.5 billion were invested elsewhere at 6%/year for 17 months = ~VND 1.1 billion in profit
- Conclusion: early payment only makes sense if you have no better investment channel for that money
Option 2 — Use the 0% loan package, keep your cash:
- Save ~VND 680 million in loan interest during the construction period
- Keep ~VND 10.5 billion for investment or to maintain liquidity
- Greater financial flexibility during the 17 months awaiting handover
In contrast to early payment discounts, the real advantage for Phase 1 buyers is not an additional discount — it is the ability to buy at the developer’s base price before secondary-market prices form after handover. According to Phú Mỹ Hưng District 7’s track record, the gap between primary prices (bought from the developer) and secondary prices (bought after handover) typically runs from 15–30% — far exceeding any early payment discount.
What Rights and Commitments Does Developer Phú Mỹ Hưng Include With the Sales Policy?
There are 4 core commitments from Phu My Hung accompanying the Hồng Hạc City sales policy: guarantees from the 3 biggest-name banks, direct signing of the sale and purchase agreement with no intermediaries, on-schedule handover and transparent terms protecting customer rights — together forming a comprehensive legal and financial protective wall for every customer entering a transaction.
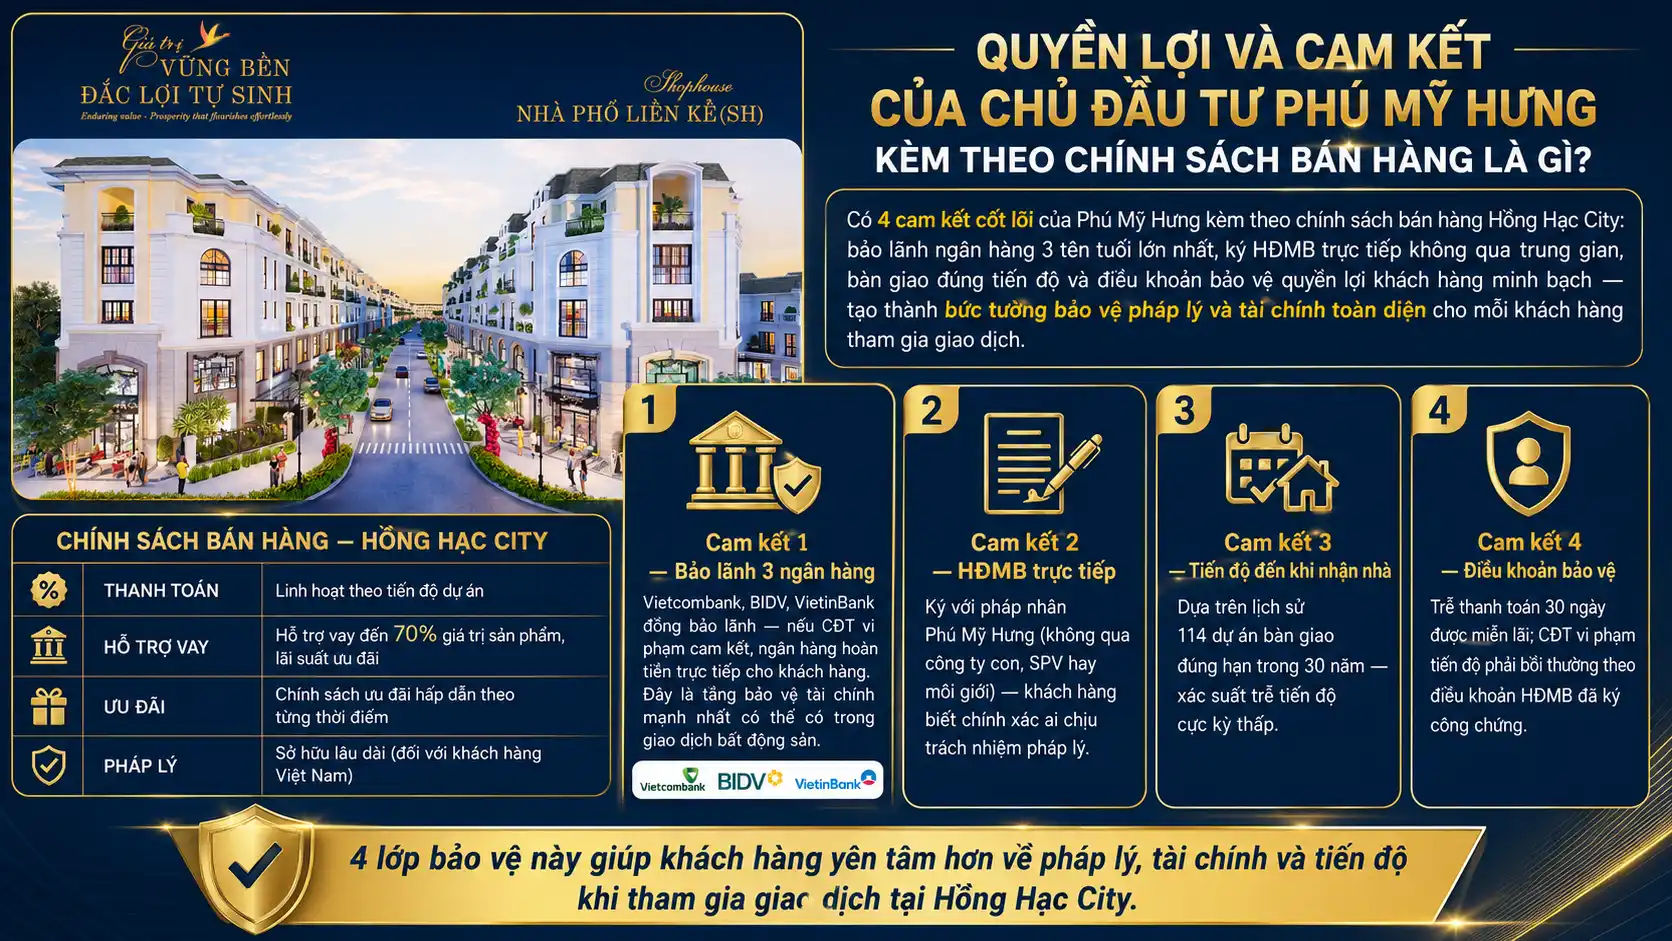
More specifically, the 4 commitments analysed from a practical perspective:
Commitment 1 — Guarantee from 3 banks: Vietcombank, BIDV and VietinBank jointly guarantee — if the developer breaches its commitments, the banks refund customers directly. This is the strongest level of financial protection possible in a property transaction
Commitment 2 — Direct sale and purchase agreement: Signed with the Phu My Hung legal entity (not via a subsidiary, SPV or broker) — customers know exactly who bears legal responsibility
Commitment 3 — Schedule through to handover: Based on a track record of 114 projects delivered on time over 30 years — the probability of delay is extremely low
Commitment 4 — Protective terms: Payments up to 30 days late are interest-free; if the developer breaches the schedule, it must pay compensation under the notarised contract terms
Which Banks Guarantee Hồng Hạc City? What Does the Guarantee Mean?
The 3 banks guaranteeing Hồng Hạc City are Vietcombank, BIDV and VietinBank — these are Vietnam’s 3 largest commercial banks by total assets, accounting for over 40% of the banking system’s total assets — the joint guarantee of all 3 banks represents the highest level of security possible in a property transaction in Vietnam.
More specifically, what does a bank guarantee mean for homebuyers:
- Absolute financial protection: If Phu My Hung breaches its handover commitment (for any reason), the guaranteeing banks have a legal obligation to refund the entire amount the customer has paid — including both the cash portion and the portion already disbursed by the bank
- A signal of independent appraisal: Vietcombank, BIDV and VietinBank each conducted independent legal and financial due diligence before agreeing to guarantee — this is the strongest “seal of quality” from a reputable third party
- Easier borrowing: A bank-guaranteed property + individual pink book for each unit = the best collateral conditions, the highest credit limit, and the most competitive interest rates
By contrast, many property projects in Bac Ninh have no bank guarantee — or only a guarantee from a small, lesser-known bank. Should the developer run into financial difficulty, customers are left with no one responsible for refunding their money — a real risk that has already materialised at numerous projects nationwide.
If Hồng Hạc City Is Handed Over Late, How Are Customers Protected?
If Hồng Hạc City is handed over late, customers are protected by 2 layers of legal mechanisms: compensation terms in the sale and purchase agreement (the developer must pay compensation based on the number of days delayed) and the bank guarantee (in the event the developer is unable to fulfil its commitments) — a dual protection system that few projects in Bac Ninh can offer.
Specifically, the customer protection terms in the Hồng Hạc City sale and purchase agreement:
- Late payment by the customer: Within 30 days — interest is waived entirely. Only after 30 days is interest charged from the due date
- Late handover by the developer: Compensation must be paid under the contractual penalty terms signed and notarised — the specific figures are stated in the agreement
- Developer unable to deliver: The guaranteeing banks (Vietcombank/BIDV/VietinBank) refund the entire amount paid
An important practical note: With Phu My Hung’s track record of 114 projects delivered on time over 30 years — even during the Covid-19 pandemic — the probability of a delayed handover at Hồng Hạc City is extremely low. These protective terms are a “backup safety net” rather than a realistic scenario to worry about.
What Are the Conditions and Procedures for Accessing Hồng Hạc City’s Financial Policies?
To access Hồng Hạc City’s financial policies, customers must meet 3 groups of conditions: income conditions (a DTI ratio of no more than 40–50%), credit history conditions (no group 3–5 bad debt) and personal legal documentation conditions (valid ID card, household registration, employment contract) — and go through 4 procedural steps from deposit to disbursement over approximately 3–4 weeks.
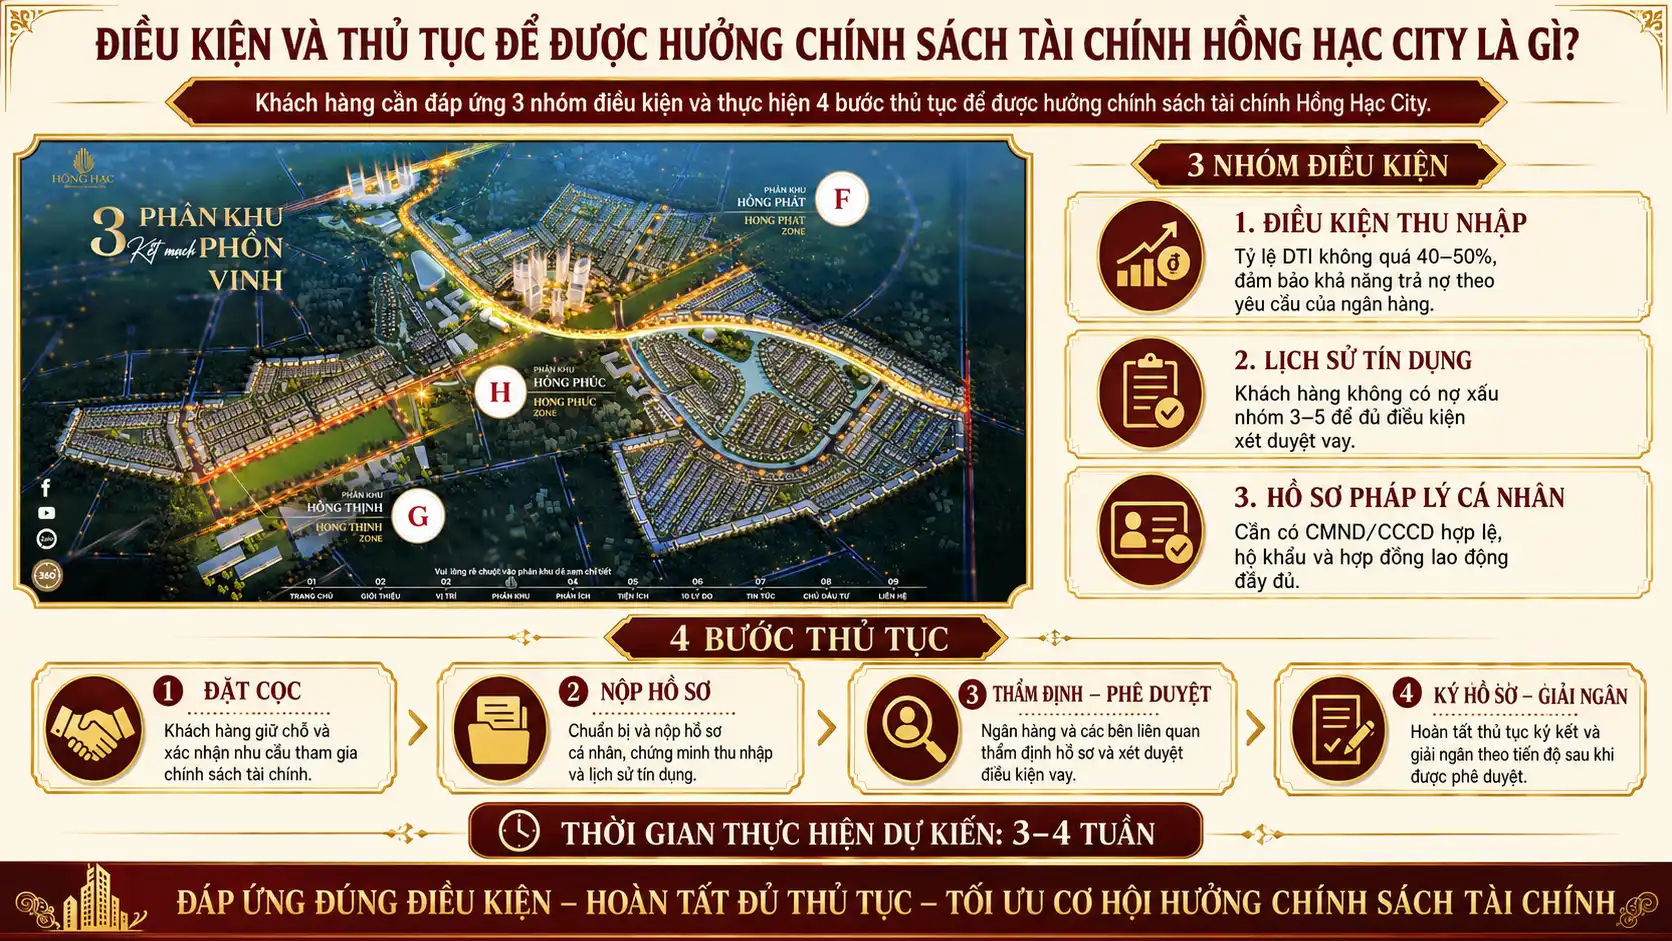
Below are the details of each procedural step:
Step 1 — Place a deposit (Week 1):
- Place a deposit of VND 200 million via bank transfer
- Receive a deposit confirmation from Phu My Hung
- Select a specific unit on the model and confirm with the Sales Department
Step 2 — Prepare the loan application (Weeks 1–2):
- ID card + household registration (originals + certified copies)
- Employment contract (still valid) + 6–12 months of salary statements
- Supplementary income documents (if you have business income)
- Marriage documents (if spouses are co-borrowing)
Step 3 — Appraisal and approval (Weeks 2–3):
- Submit the application to one of the 3 guaranteeing banks
- The bank assesses income and credit history
- Approval is usually given within 7–10 working days
Step 4 — Sign the Sales and Purchase Agreement and disbursement (Weeks 3–4):
- Pay the full 20% (deposit + 15% + VAT) in order to sign the Sales and Purchase Agreement
- Sign the Sales and Purchase Agreement directly with Phu My Hung
- The bank begins monitoring construction progress to disburse in instalments
More importantly, as Hong Hac City already has a separate land use certificate for each property — the “cleanest” possible collateral — the bank’s appraisal process is typically faster and less complicated than for projects without certificates. This is an intangible but very real advantage, especially for buyers who need quick disbursement to secure a property before stock runs out.
Is Hong Hac City’s Sales Policy Attractive Compared to Other Projects in Bac Ninh and Surrounding Areas?
Hong Hac City stands out for its financial security (guarantees from the three largest banks + 0% interest until handover + principal grace period); Vinhomes Ocean Park excels in brand recognition and secondary-market liquidity in Hanoi; and Ecopark offers the most accessible pricing and a fully matured ecosystem — each project best serves a different group of buyers.
Hong Hac City’s unique highlight in this policy comparison: a full principal grace period until the handover date is an extremely rare policy in the premium villa and townhouse segment in the North — most projects in the same segment only offer a 6–12 month principal grace period, after which buyers must pay both principal and interest even though their homes have not yet been handed over.
How Does Hong Hac City’s Financial Policy Differ from Vinhomes Ocean Park and Ecopark?
Hong Hac City leads in financial security, with guarantees from the three largest banks, 0% interest throughout the construction phase and a full principal grace period; Vinhomes Ocean Park offers flexible borrowing policies, but post-grace interest rates are usually higher and the principal grace period is shorter; Ecopark has a flexible progress-based payment schedule but no simultaneous guarantee from the three largest banks.
Conclusion for buyers seeking maximum financial safety: Hong Hac City offers the best risk-protection policy of the three options. Conclusion for investors focused on secondary-market liquidity: Vinhomes Ocean Park has a more developed secondary market thanks to its larger scale and closer proximity to Hanoi. Conclusion for buyers on a limited budget: Ecopark offers more accessible pricing with flexible payment policies.
Can a Hong Hac City Sales and Purchase Agreement Be Transferred Before Handover?
Yes — a Hong Hac City Sales and Purchase Agreement can be transferred before handover, but three conditions must be met: all financial obligations up to the time of transfer must be fully discharged; written consent and approval must be obtained from the developer Phu My Hung; and a transfer fee must be paid as stipulated (typically 1–2% of the contract value — the exact amount should be confirmed with the sales department at each point in time).
What this means for investors: transferring the Sales and Purchase Agreement before handover is a quick exit mechanism if liquidity is needed, and is particularly useful if the secondary market rises sharply after 2026, once Ring Road 4 and Gia Binh Airport come into operation. However, this is a contingency mechanism — the optimal strategy remains holding the property until handover and for a further 3–5 years to benefit fully from the price appreciation driven by completed infrastructure.