There are currently 6 banks supporting home loans for Hồng Hạc City Phú Mỹ Hưng, namely BIDV, VietinBank, Vietcombank, VIB, ACB and Standard Chartered, with maximum loan-to-value ratios of 70 to 75% of the sale and purchase contract value, an interest rate of 0% and a full principal repayment grace period until handover. In particular, this is the first time a property project in northern Vietnam has simultaneously involved a state-owned bank, domestic private banks and an international bank within the same financial ecosystem. More importantly, this diversity of banking partners gives homebuyers complete freedom to choose the loan package best suited to their personal financial capacity.
In terms of specific conditions, customers can borrow up to 70% of the contract value from state-owned banks, or up to 75% if they choose Standard Chartered, with a maximum loan term of 25 years. In addition, the principal repayment grace period and 0% interest policy, lasting from the signing of the sale and purchase contract until handover, significantly reduce buyers’ cash-flow pressure during construction. Furthermore, the developer, Phú Mỹ Hưng, will also provide an additional 3% interest-rate subsidy for the first 12 months after handover, reducing the actual interest rate payable by buyers to approximately 4.3–4.4% per year, an extremely competitive level in today’s market.
In terms of legal status and reliability, the participation of Standard Chartered, an international financial institution with stringent assessment standards, is the clearest indication that Hồng Hạc City has completed all the necessary legal documentation. Furthermore, the project has more than 1,000 units in the Hồng Phát subdivision that have been issued long-term ownership Pink Books, providing customers with maximum convenience during the loan and property-mortgage process. Explore all the details of each bank, the lending conditions and how to choose the most suitable financial package below.
What Is the Hồng Hạc City Phú Mỹ Hưng Home Loan Policy?
The Hồng Hạc City home loan policy is an integrated financial support scheme implemented by Phú Mỹ Hưng through partnerships with 6 partner banks, allowing buyers to borrow up to 70–75% of the contract value at 0% interest, with a full principal repayment grace period until handover.
More specifically, the financial policy at Hồng Hạc City is structured into 3 clearly defined preferential stages, enabling homebuyers to plan their finances proactively and transparently throughout the property ownership lifecycle:
Phase 1 – From signing the contract to taking possession (0% interest): From the time the Sale and Purchase Agreement is signed, buyers receive a full grace period on principal repayments and 0% interest until they take possession according to the handover schedule. During this phase, buyers only need to make payments according to the contract schedule, with no loan interest incurred.
Phase 2 – First 12 months after handover (3% interest-rate support from the developer): After handover, Phú Mỹ Hưng Development Corporation continues to provide direct support of 3% per year against the total bank interest rate applicable to loans of up to 75% of the Sale and Purchase Agreement value. This means the buyer’s actual interest rate is only around 4.3–4.4% per year when combined with Standard Chartered’s fixed-rate package.
Phase 3 – After the 12-month support period (market interest rates): From the 13th month after handover onwards, interest is calculated at the market rate applied by the bank. However, by this point the property will have entered stable operation or use, and cash flow from leasing or operating a shophouse may provide significant support for debt repayments.
In addition, all loan packages at Hồng Hạc City require payment by bank transfer in accordance with the Ministry of Construction’s anti-money-laundering regulations, ensuring transparency and legal compliance for all financial transactions.
Which Banks Currently Support Loans for Purchasing at Hồng Hạc City?
There are 6 banks officially supporting loans for purchasing at Hồng Hạc City, divided into 2 groups: state-owned banks comprising BIDV, VietinBank and Vietcombank, and private and international banks comprising VIB, ACB and Standard Chartered. Each group has its own features and advantages to suit different customer segments.
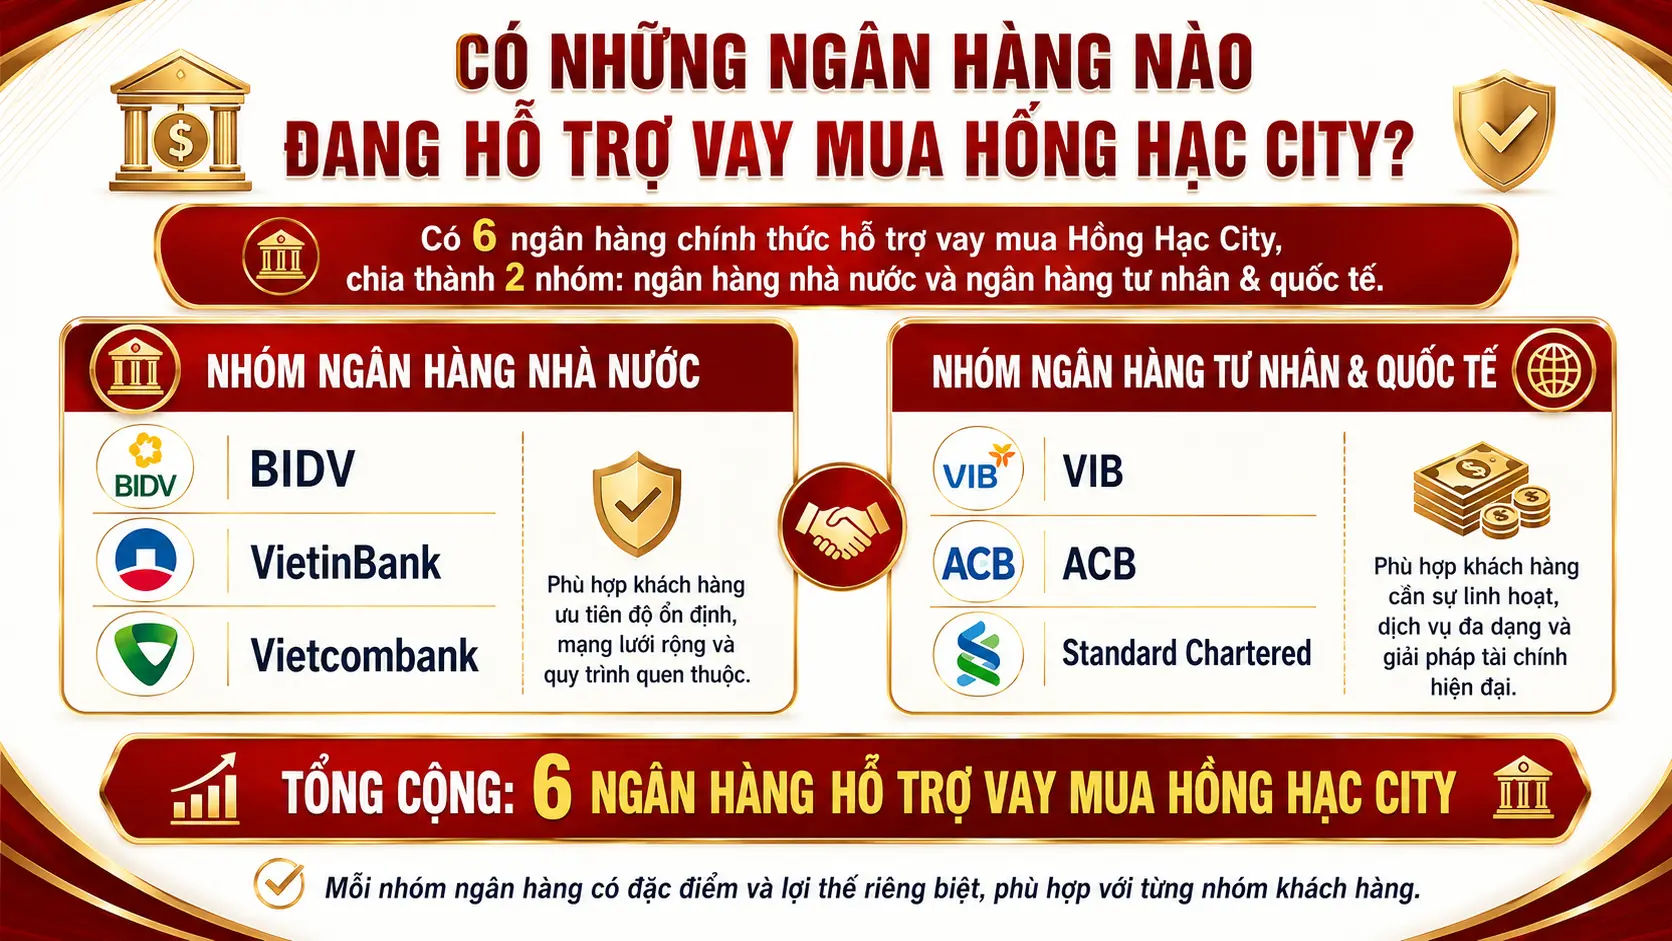
Below is a detailed analysis of each banking group to help buyers make an informed choice:
Which State-Owned Banks Support Loans for Hồng Hạc City?
There are 3 state-owned banks supporting loans for purchasing at Hồng Hạc City: Vietcombank (VCB), BIDV and VietinBank. These are also the 3 banks that have signed official cooperation agreements with Phú Mỹ Hưng Development Corporation and simultaneously act as project guarantee banks in accordance with the Law on Real Estate Business.
Specifically, the role and conditions offered by each state-owned bank at Hồng Hạc City are distinguished as follows:
Vietcombank (VCB):
- Vietnam’s largest state-owned commercial bank by market capitalisation, joining Hồng Hạc City’s financial ecosystem from the first sales launch in June 2025
- Provides loans of up to 70% of the Sale and Purchase Agreement value, with principal and interest deferred at 0% until handover
- Also acts as the guarantee bank, issuing a guarantee certificate for each individual home and providing maximum financial protection for buyers
BIDV:
- Joined Hồng Hạc City’s lending ecosystem at the opening of the Phú Mỹ Hưng Sales Centre in Hanoi on 3 October 2025, where BIDV directly presented financial solutions and preferential loan packages
- Provides loans of 70% of the Sale and Purchase Agreement value, with principal and interest deferred at 0% until handover
- Provides project guarantees in accordance with the law, creating an additional layer of financial protection for customers
VietinBank:
- One of the first 3 state-owned banks to sign a cooperation agreement with Phú Mỹ Hưng for the Hồng Hạc City project
- Provides loans of 70% of the property value, at 0% interest, with principal deferred from the signing of the Sale and Purchase Agreement until handover
- Also performs the project guarantee function, ensuring that a guarantee certificate for each home is fully issued before the customer signs the contract
More importantly, the fact that all 3 of Vietnam’s largest state-owned banks are simultaneously guaranteeing Hồng Hạc City is the clearest evidence of the project’s legal transparency and the ability of Phú Mỹ Hưng Development Corporation to complete it on schedule.
Which Private and International Banks Participate in Hồng Hạc City’s Loan Package?
There are 3 private and international banks participating in Hồng Hạc City’s loan package: VIB, ACB and Standard Chartered. They offer greater variety in interest-rate structures and loan-to-value ratios, particularly the option of fixed interest rates and loan-to-value ratios of up to 75%, which the state-owned banks do not currently offer.
Specifically, the key features of each bank in this group are as follows:
VIB (Vietnam International Bank):
- Signed a financial-support cooperation agreement with Phú Mỹ Hưng Development Corporation at the opening ceremony of the Hanoi Sales Centre in October 2025
- Provides loans of 70% of the Sale and Purchase Agreement value, with preferential interest-rate policies and flexible loan terms
- Suitable for customers who already have an established credit relationship with VIB or wish to take advantage of multi-service combined loan products
ACB (Asia Commercial Bank):
- Participates alongside VIB in Hồng Hạc City’s financial ecosystem, offering an additional reputable private-bank option with a large retail customer base
- Provides loans under preferential policies linked to the developer, with flexible procedures suited to entrepreneurs and self-employed customers
Standard Chartered:
- The only international bank in Hồng Hạc City’s lending ecosystem, with an official financial-advisory event held on 20 December 2025 at the project’s Sales Gallery
- Offers the highest loan-to-value ratio in the system, of up to 75% of the secured asset value, with loan terms of up to 25 years
- Its sole distinctive feature: a fixed-rate package that is unaffected by market fluctuations during the initial period, suitable for investors who need to forecast long-term cash flow accurately
What Are the Loan Conditions and Payment Schedule for Purchasing at Hồng Hạc City?
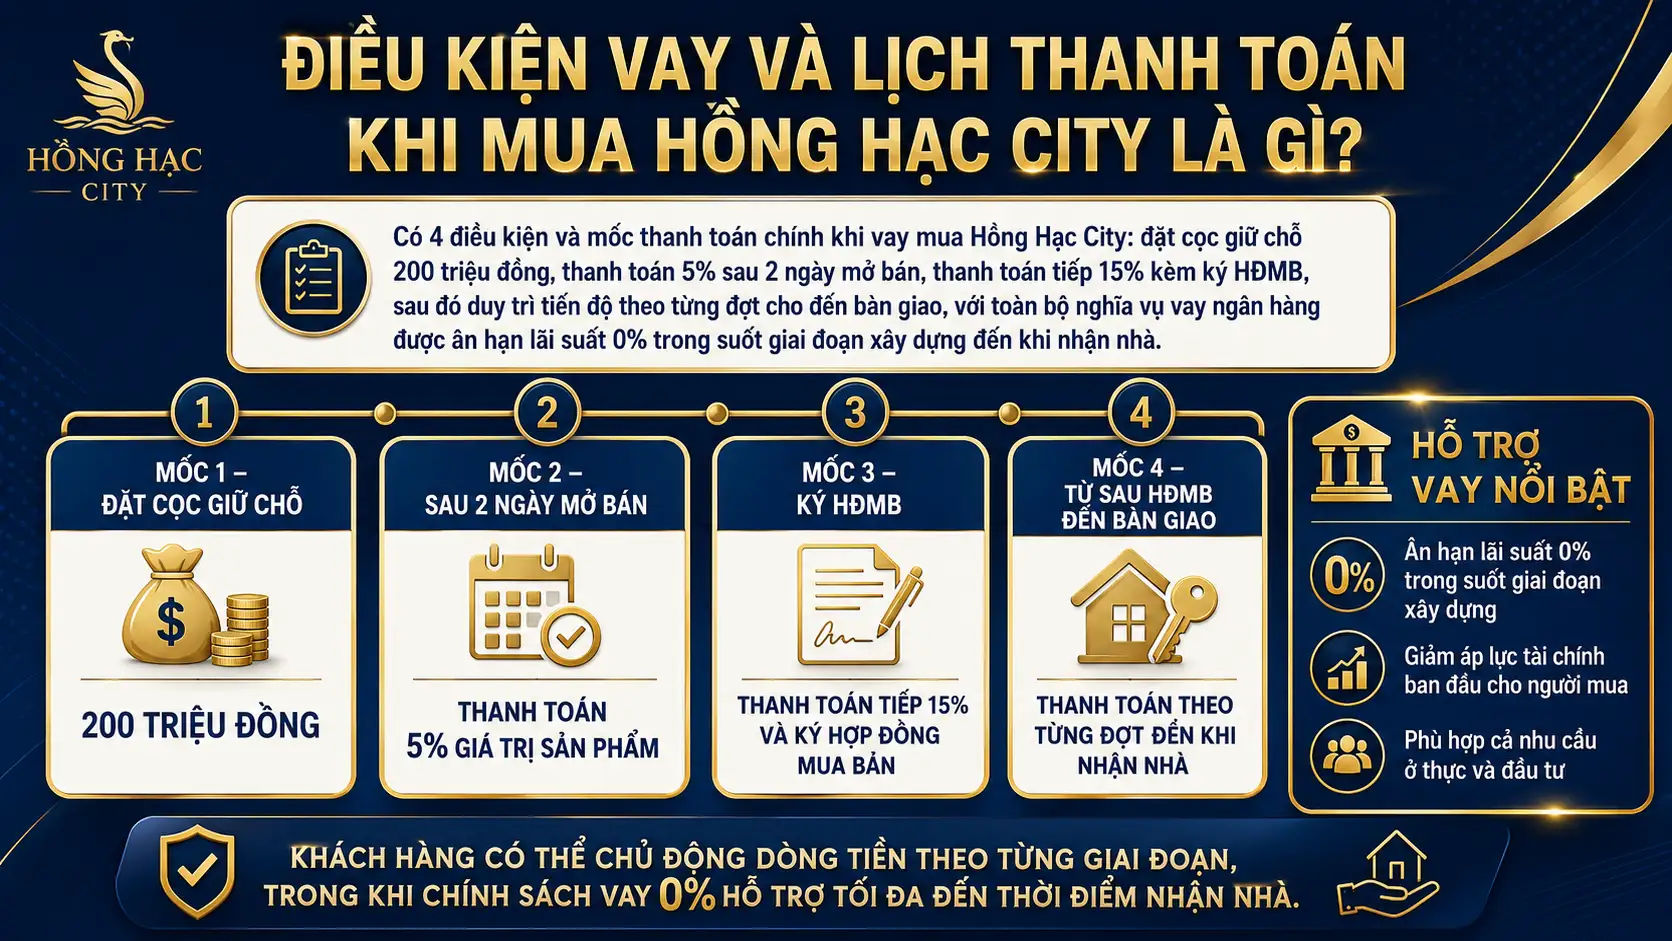
There are 4 main conditions and payment milestones when taking out a loan to purchase at Hồng Hạc City: a VND 200 million reservation deposit, payment of 5% 2 days after the sales launch, a further 15% payment upon signing the Sale and Purchase Agreement, followed by payments according to the instalment schedule until handover, with all bank-loan obligations subject to 0% interest deferral throughout the construction period until handover

Below are details of the grace-period mechanism and preferential interest-rate policies to help buyers understand their actual financial obligations:
How Does the Principal-Deferral and 0% Interest Mechanism at Hồng Hạc City Work?
The principal-deferral and 0% interest mechanism involves the partner bank disbursing the loan immediately after the Sale and Purchase Agreement is signed, while the borrower does not have to repay any principal or interest until officially taking possession. All interest costs incurred during this period are paid by Phú Mỹ Hưng Development Corporation.
For a specific illustration, a customer purchasing a Hồng Hạc City townhouse valued at VND 8 billion and borrowing 70% (VND 5.6 billion) according to the schedule below would have the following actual financial obligations:
The Hồng Hạc City project payment schedule is summarised in the table below, including each time milestone, payment percentage and corresponding bank-loan obligation:
| Date | Details | Percentage / Amount (using VND 8 billion as an example) | Loan interest obligation |
| 19/4/2025 | Reservation booking | VND 200 million | None |
| 14/6/2025 | Sales launch, signing of the deposit agreement | Select the unit | None |
| 16/6/2025 | 1st payment | 10% excluding VAT = VND 800 million | None |
| 14/7/2025 | 2nd instalment + signing of the Sale and Purchase Agreement | 10% + VAT = approximately VND 880 million | 0% interest, principal deferred |
| Subsequent instalments | According to construction progress | 5% per instalment / every 3 months | 0% interest, principal deferred |
| Handover (June 2027) | Final instalment of 45% + 50% VAT | Pay the remaining balance | Begin repaying principal + interest |
Therefore, throughout the entire period from signing the Sale and Purchase Agreement to handover (approximately 18–24 months), buyers incur no interest burden whatsoever on the bank loan. This is an extremely valuable financial advantage compared with most property projects currently on the market, which require borrowers to pay interest from the first month of disbursement.
How Does the 3% Interest-Rate Support Policy Apply After Handover?
The 3% post-handover interest-rate support policy is Phú Mỹ Hưng Development Corporation’s commitment to paying 3% per year directly against the total bank interest rate applicable to loans of up to 75% of the Sale and Purchase Agreement value, continuously for the first 12 months after the customer takes possession under the contract.
Specifically, the mechanism works as follows: if the bank applies an interest rate of 7.3–7.4% per year during the post-handover period, the developer will provide 3% support, meaning the buyer only actually pays 4.3–4.4% per year. This actual rate is only marginally higher than bank savings rates, creating an opportunity to invest in and operate the property with a very low cost of capital during the first year.
Furthermore, for investors purchasing shophouses or townhouses for commercial rental, rental income during the first 12 months after handover can fully cover and even exceed the 4.3–4.4% per annum interest obligation, making Hong Hạc City a self-financing asset from its first year of operation.
How Do the Loan Conditions Differ Between the Banks Supporting Hong Hạc City?
BIDV, VietinBank and Vietcombank excel in legal guarantee credibility and standardised procedures; VIB and ACB are better in terms of flexibility and approval speed for self-employed customers; Standard Chartered is the most advantageous in terms of the highest loan-to-value ratio (75%) and a stable long-term fixed interest rate.
The table below provides a comprehensive comparison of the key lending criteria across the 6 partner banks of Hong Hạc City, helping buyers make a quick comparison and the most suitable decision:
| Bank | Maximum loan-to-value ratio | Loan term | Interest rate type | Guarantee role | Best suited to |
| Vietcombank | 70% of the sale contract value | 20–25 years | Variable | Yes (project guarantee) | Customers prioritising maximum legal security |
| BIDV | 70% of the sale contract value | 20–25 years | Variable | Yes (project guarantee) | Customers with an existing relationship with BIDV |
| VietinBank | 70% of the sale contract value | 20–25 years | Variable | Yes (project guarantee) | Corporate customers and government officials |
| VIB | 70% of the sale contract value | 20–25 years | Variable / fixed | No | Young customers seeking flexibility and rapid application approval |
| ACB | 70% of the sale contract value | 20–25 years | Variable | No | Self-employed customers and SME entrepreneurs |
| Standard Chartered | 75% of the secured asset value | Up to 25 years | Fixed | No | Investors requiring interest-rate stability and the maximum loan amount |
However, the most important difference lies not in the loan-to-value ratio but in the interest rate type: while the other 5 banks all apply variable rates (adjusted every 3–6 months after the preferential period), Standard Chartered offers a fixed-rate package for a specified period, allowing borrowers to know their exact financial obligations without worrying about market interest-rate fluctuations.
Conversely, variable rates from state-owned banks have an advantage when the market is trending towards lower interest rates, as borrowers benefit immediately without being tied to a higher fixed rate. This is a factor that should be carefully considered based on each individual’s interest-rate outlook and investment timing.
Are Any Special Documentation Requirements Needed to Obtain a Loan to Buy at Hong Hạc City?
No, obtaining a loan to buy at Hong Hạc City does not require any special documentation beyond the usual property loan process, for at least 3 fundamental reasons: the project has complete legal documentation, more than 1,000 units in the Hồng Phát precinct have been issued with freehold Certificates of Ownership, and the properties have full guarantee certificates from state-owned banks.
Specifically, the documentation for a loan to buy at Hong Hạc City comprises the following standard groups of documents:
Group 1 – Personal documents:
- Valid identity card/citizen identity card
- Household registration book or residence confirmation
- Marriage certificate or confirmation of single status (if applicable)
Group 2 – Income documents:
- Employment contract and salary statements for the most recent 3–6 months (for salaried employees)
- Business registration certificate and financial statements (for self-employed applicants)
- Bank account statements for the most recent 6–12 months
Group 3 – Sale contract documents:
- Deposit agreement or Sale Contract signed with Phú Mỹ Hưng Development Corporation
- Individual unit guarantee certificate issued by a state-owned bank
- Original price list confirmed by the developer, certifying the property’s value
More importantly, Hong Hạc City’s transparent legal framework provides a significant advantage over most newly launched projects: the fact that each unit already has an available Certificate of Ownership not only speeds up the mortgage process but also enables banks to value the property more accurately, resulting in a higher loan approval rate and significantly shorter application processing times. According to information from Phú Mỹ Hưng’s sales department, the entire process from application submission to disbursement has been optimised for completion as quickly as possible, helping customers avoid missing the opportunity to buy during the limited launch period.
What Does Standard Chartered’s Participation Mean for Hong Hạc City Buyers?
Yes, Standard Chartered’s participation has significance beyond purely financial matters for at least 3 important reasons: it is a signal that the project’s legal credentials have been assessed by an international institution with the highest risk standards, while also providing a unique fixed-interest-rate option not previously available in the Bắc Ninh property market, and confirming that Hong Hạc City meets international standards for access to foreign-currency funding.
Specifically, within the international banking system, Standard Chartered is renowned for its extremely stringent credit and property-project assessment procedures. The bank only approves funding for a project once it has passed a set of criteria assessing its legal status, progress, developer capability and asset liquidity. This means that Standard Chartered’s presence in the Hong Hạc City ecosystem serves as an “implicit certification” of the project’s quality, carrying considerably more weight than any marketing material. Furthermore, this is the first property project in Bắc Ninh to involve a major international bank, establishing a new precedent for transparency and financial safety standards in the regional market.
How Does Standard Chartered’s Fixed-Rate Loan Package Differ from the Variable-Rate Packages at State-Owned Banks?
Standard Chartered’s fixed interest rate excels in predictability and long-term cash-flow control, while the variable rates from VCB, BIDV and VietinBank are better for benefiting flexibly when market interest rates fall. Those prioritising stability and wishing to avoid the risk of fluctuations should choose Standard Chartered; those who believe market interest rates will fall in the medium term and have flexible finances should choose a state-owned bank. The key point is that a fixed rate suits investors who need to plan cash flow precisely for the first 3–5 years, particularly when operating a shophouse commercially and needing to calculate the break-even point clearly.
Which Bank Should Hồng Hạc City Buyers Choose for Their Financial Circumstances?
The optimal bank depends on the individual’s financial profile: Group 1 – Buyers preparing at least 50% of the capital themselves should choose VCB or BIDV because of their standardised procedures, rapid approval and comprehensive guarantees. Group 2 – Buyers requiring the maximum loan to optimise financial leverage should choose Standard Chartered (75%) or VIB; the high loan-to-value ratio leaves more cash available for other investment opportunities. Group 3 – Self-employed buyers with irregular income should prioritise ACB or VIB, as these two banks are more flexible when assessing entrepreneurs’ income. Group 4 – Buyers prioritising absolute interest-rate stability can only be accommodated by Standard Chartered’s long-term fixed-rate package.