The interest rates for purchasing Hồng Hạc City comprise 2 clearly defined phases: a 0% phase covering the entire period from signing the sale and purchase contract (7/2025) until handover (12/2026), followed by a preferential interest-rate phase after handover from the 3 official partner banks, Vietcombank, BIDV and VIB. In particular, developer Phú Mỹ Hưng also provides additional support of 3% per annum during the first 12 months after handover, creating a “two-layer financial protection” mechanism lasting more than 30 months in total—an uncommon privilege in the conventional property market.
Comparing the 3 banks, Vietcombank leads in brand reputation and service ecosystem; BIDV performs well in flexible fixed-rate terms and support policies for first-time buyers; while VIB is optimal for its diverse range of flexible long-term fixed-rate packages. In addition, loan applicants must meet 4 main groups of requirements covering income, credit history, personal legal documentation and collateral, consistently across all 3 banks.
In terms of competitiveness, the Hồng Hạc City purchase-loan interest rate is significantly lower than the market range of 8–14% per annum in May 2026, thanks to incentives from the developer that can generate savings of up to billions of đồng during the first 18-month grace period. Explore the complete interest-rate structure, loan conditions and comparison of the 3 banks in the article below.
What types of interest rates are available for purchasing Hồng Hạc City?
There are 2 main types of interest rates when taking out a loan to purchase Hồng Hạc City, classified by period: 0% interest (the grace period until handover) and preferential bank interest rates (the post-handover period), combined with 3% per annum support from the developer during the first 12 months after receiving the property.
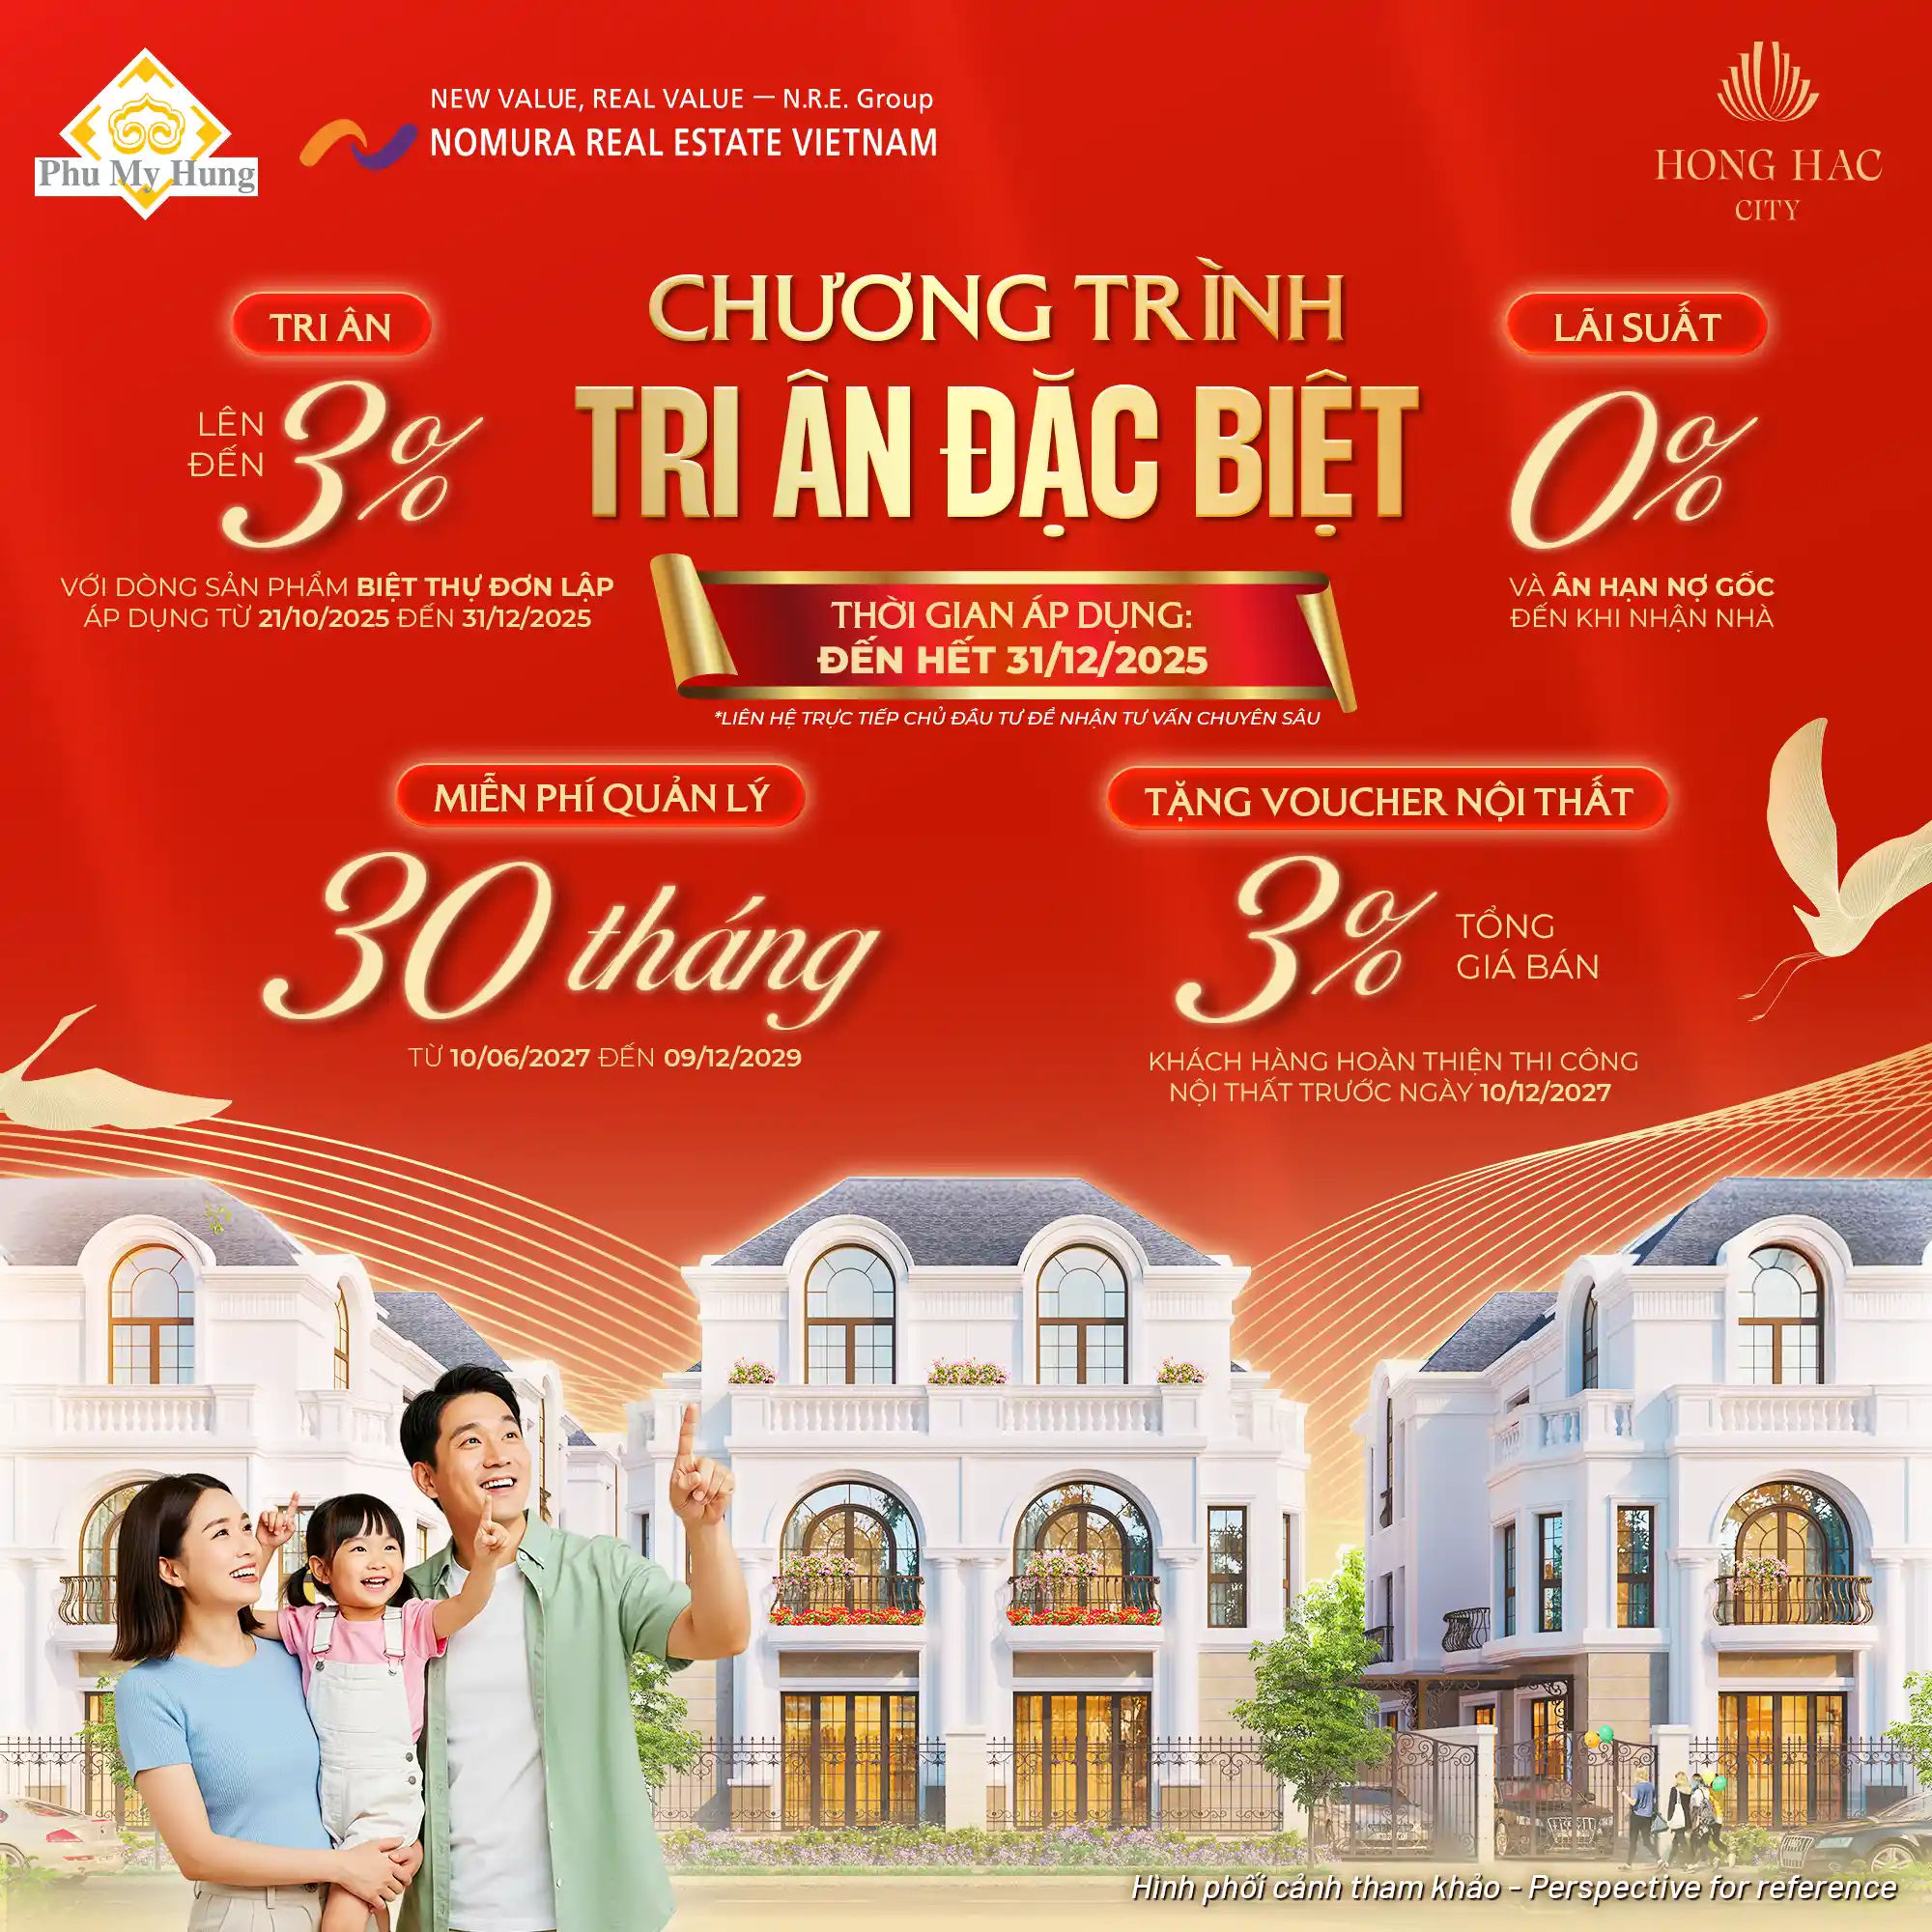
Below is a summary table of the loan interest-rate structure over its entire term when purchasing Hồng Hạc City, giving investors an overview in 30 seconds before examining each detailed phase:
The table below describes the interest-rate structure for each period of the Hồng Hạc City purchase loan, from contract signing until the end of the preferential period:
| Phase | Journey time | Applicable interest rate | Provider of support |
| Before handover | 7/2025 to 12/2026 (~18 months) | 0% (full grace period for principal and interest) | PMH developer + bank |
| First 12 months after handover | 1/2027 to 12/2027 | Bank interest rate minus 3% per annum | Bank + 3% support from PMH |
| After the developer incentive ends | From 1/2028 onwards | Standard bank interest rate | Bank |
More specifically, the “two-layer financial protection” mechanism creates 2 periods of particularly low financial costs: a completely interest-free period (18 months at 0%) and a period of sharply reduced costs (12 months with 3% per annum support). In addition, all 3 partner banks—Vietcombank, BIDV and VIB—apply this 0% grace-period mechanism consistently under their implementation agreements with developer Phú Mỹ Hưng.
During which period does the 0% interest rate apply when purchasing Hồng Hạc City?
The 0% interest rate when purchasing Hồng Hạc City is a full grace-period mechanism covering both principal and interest. It applies to 100% of the bank-financed portion—up to 70% of the property value—from the date the sale and purchase contract is signed until the expected handover date of 10/12/2026. This is approximately 18 months without any loan-interest costs being incurred.
More specifically, the practical meaning of 0% interest is that throughout the construction period, the entire bank loan—for example, VND 14 billion when purchasing a VND 20 billion townhouse—is not charged daily interest. As a result, this money remains entirely in the investor’s bank account and may generate additional returns through savings or other investments during the same period. Below is a detailed analysis of each applicable condition and the support policy after handover.
What are the conditions for receiving 0% interest when taking out a loan to purchase Hồng Hạc City?
The conditions for receiving 0% interest when taking out a loan to purchase Hồng Hạc City comprise 3 basic requirements: purchasing directly from developer Phú Mỹ Hưng during the official launch on 14/6/2025, signing a loan agreement with one of the 3 official partner banks—Vietcombank, BIDV or VIB—and complying with the schedule for the buyer’s own-payment portion under the sale and purchase contract.
Specifically, this mechanism applies equally to all property types: townhouses (terraced houses), shophouses (commercial townhouses), semi-detached villas and detached villas, regardless of the property price. In addition, the 0% interest rate applies only to the bank-financed portion—up to 70% of the value; the payments made directly according to the schedule—an initial 20% and subsequent 5% instalments—are paid normally according to the schedule and are unrelated to the grace-period mechanism. More importantly, investors must register and have their loan approved by a partner bank before signing the sale and purchase contract to ensure they receive the correct project-linked incentive package and avoid borrowing after signing without receiving the 0% rate.
What is the developer’s 3% per annum interest-rate support programme after handover?
The 3% per annum interest-rate support programme after handover is an additional financial incentive from developer Phú Mỹ Hưng, lasting 12 months from the date of handover—from 1/2027 to 12/2027—during which PMH directly funds 3 percentage points of the annual interest rate on the customer’s entire remaining bank-loan balance.
Specifically, if the bank’s applicable interest rate from January 2027 is 10% per annum, the customer will actually pay only 7% per annum during those 12 months—PMH pays the 3% difference directly to the bank under the interest-rate support mechanism. In addition, this is the second layer of financial protection after the 0% period, creating a smooth transition from zero costs to the full market interest rate, thereby giving investors sufficient time to stabilise cash flow from business activities or leasing before bearing the full burden of standard loan interest. Furthermore, the mechanism creates a “preferential financial period” lasting from 7/2025 to 12/2027 in total, meaning that during the first 2.5 years, investors always pay significantly less interest than the conventional market rate.
What are the interest rates offered by the 3 banks providing loans to purchase Hồng Hạc City?
There are 3 banks providing loans to purchase Hồng Hạc City as official partners of developer Phú Mỹ Hưng: Vietcombank, BIDV and VIB. Each bank has its own features regarding preferential interest rates, fixed-rate terms and conditions after the preferential period ends.
Below is a detailed analysis of each bank to help investors compare and select the loan package best suited to their financial profile and ownership objectives.
How does Vietcombank provide loans for purchasing Hồng Hạc City?
Vietcombank is Vietnam’s leading state-owned commercial bank. It offers loans for purchasing Hồng Hạc City with a maximum loan-to-value ratio of 70% of the collateral value, a term of up to 25 years and the full benefit of the 0% grace-period mechanism from sale and purchase contract signing until handover.
Specifically, after the 0% period, Vietcombank applies a fixed preferential interest rate during the initial period—typically 6 to 24 months, depending on the selected package—before switching to a floating rate referenced to the deposit rate plus a margin under the policy applicable at each time. In addition, Vietcombank has an extensive branch network throughout Bắc Ninh and neighbouring provinces, thereby making it convenient for investors from different areas to complete their applications and draw down their loans. In particular, as a state-owned bank, Vietcombank has an advantage in terms of legal reliability and generally prioritises applications from customers purchasing projects by reputable developers such as Phú Mỹ Hưng, which helps shorten application approval times compared with the market average.
Note: Specific interest rates change from time to time. Investors should contact Vietcombank directly or the Phú Mỹ Hưng sales department for an accurate quotation at the time of purchase.
How does BIDV provide loans for purchasing Hồng Hạc City?
BIDV (Bank for Investment and Development of Vietnam) offers loans for purchasing Hồng Hạc City with a maximum loan-to-value ratio of 70% of the collateral value, a term of up to 25 years and the full benefit of the 0% grace-period mechanism during the construction phase.
Specifically, BIDV’s distinctive strength in the property lending segment is its policy of supporting first-time homebuyers and its loan packages with flexible fixed-interest periods (typically from 12 to 36 months), after which rates become floating based on the internal reference rate plus a margin. In addition, BIDV has extensive experience in lending to large-scale property projects in Bắc Ninh and the key northern economic region, thereby enabling it to optimise the collateral valuation and application-processing procedures more effectively than banks with less experience in this market. Furthermore, BIDV often runs promotional programmes by quarter and on special occasions, so investors should check the latest information when applying to obtain the best available terms.
Note: Specific interest rates vary from time to time. Investors should contact BIDV directly for an accurate quotation.
How does VIB provide loans for purchasing a Hồng Hạc City property?
VIB (Vietnam International Bank) offers loans for purchasing a Hồng Hạc City property, with a maximum loan-to-value ratio of 70% of the collateral value, a loan term of up to 25 years and the full benefit of a 0% grace-period arrangement during construction, standing out for the variety and flexibility of its long-term fixed-rate packages.
Specifically, VIB is highly regarded for its flexibility in designing property loan packages: it offers more fixed-rate term options (from 12 to 60 months) than state-owned banks such as Vietcombank and BIDV, making it more suitable for investors seeking firm long-term financial planning with fixed borrowing costs during the first 3 to 5 years after handover. In addition, VIB has a fast approval process and a well-developed digital banking service, which significantly shortens the time needed to complete loan applications and receive disbursement compared with traditional banks. In particular, investors comparing post-reset floating rates should pay close attention to the margin added to VIB’s reference rate, as this determines the actual long-term cost.
Note: Specific interest rates vary from time to time. Investors should contact VIB directly for an accurate quotation at the time of application.
What requirements must be met to obtain a loan for purchasing a Hồng Hạc City property?
There are 4 main groups of requirements that apply equally to all 3 banks when borrowing to purchase a Hồng Hạc City property: proof of income, credit history, personal legal documentation and collateral, with each group having specific requirements that investors should prepare before submitting an application.
Below is a summary table of the 4 groups of requirements for a Hồng Hạc City purchase loan, helping investors assess their eligibility and prepare a complete application:
| Requirement group | Specific requirements | Notes |
| Proof of income | Minimum monthly income sufficient to service the debt (the debt-service ratio generally must not exceed 50% of income) | 6 months of bank statements or an employment contract/business licence is required |
| Credit history | No bad debts in groups 3, 4 or 5; the current debt ratio must remain within a safe range | Check CIC before submitting the application to avoid rejection |
| Personal legal documentation | A valid CCCD/CMND, household registration/KT3, and marriage or single-status certificate | For married couples, documents from both parties are required |
| Collateral | The property purchased at Hồng Hạc City itself | A separate red book for each property, with issuance directed by the Bắc Ninh People’s Committee — providing clearly defined collateral |
In addition, the minimum required income depends directly on the property value and loan ratio. Specifically, consider this practical example: if borrowing VND 14 billion (70% of a VND 20 billion townhouse) over 25 years, after the approximately 30-month promotional period ends, the estimated monthly principal and interest payments will range from VND 90 million to VND 140 million, depending on the interest rate. Applying the rule that debt repayments must not exceed 50% of income, the household’s minimum required income would be approximately VND 180 million to VND 280 million per month. Accordingly, investors should carefully calculate their long-term repayment capacity before signing a loan agreement, paying particular attention to the period after the promotional terms end, when the interest rate becomes market-floating. Furthermore, the legal status of separate red books for each property, whose issuance was directed by the Bắc Ninh Provincial People’s Committee before 25/3/2025, is a major advantage when approving loan applications, as the bank can clearly identify the collateral from the outset.
Is the interest rate for purchasing a Hồng Hạc City property lower than the market average?
Yes, the interest rate for purchasing a Hồng Hạc City property is significantly lower than the market average based on at least 3 specific factors: a 0% rate for 18 months compared with the current market range of 8–14% per year, additional support of 3% per year from the developer for the following 12 months, and a total 30+ month period of financial protection that is unprecedented among conventional property projects in Bắc Ninh.
Specifically, a practical calculation illustrates the savings: an investor borrowing VND 14 billion (70% of a VND 20 billion townhouse) for an 18-month grace period would, at the market rate of 10% per year over the same 18 months, have to pay total interest of VND 14,000,000,000 × 10% × 1.5 = VND 2,100,000,000. This means the investor would save an estimated more than VND 2 billion in interest during the 0% period alone — equivalent to approximately 10% of the value of a standard townhouse.
In addition, during the following 12 months after handover, with support of 3% per year from the developer, assuming a bank interest rate of 10% per year, the investor would effectively pay only 7% per year — saving an estimated VND 420 million compared with a conventional market-rate loan. In total, over the 30-month promotional period, the investor would save more than VND 2.5 billion compared with borrowing at the market rate of 10% per year, thereby directly improving the investment profit margin and shortening the payback period for the entire investment.
Which bank should you borrow from to optimise costs when purchasing a Hồng Hạc City property?
Vietcombank leads in brand reputation and fast approval for the Phú Mỹ Hưng project, BIDV is stronger in first-time homebuyer support policies and Bắc Ninh market experience, while VIB offers greater flexibility in long-term fixed-rate packages for investors seeking firm cost control.
Below is a comparison by total cost and actual savings to help investors make a decision suited to their personal financial profile.
Comparison of total borrowing costs at 3 banks when purchasing a Hồng Hạc City townhouse
To compare the total borrowing costs at the 3 banks, investors should focus on the floating rate after the fixed-rate period ends (from the 13th month after handover onwards), as this period accounts for most of the total interest cost over 25 years. Specifically, a 1-percentage-point difference in the floating rate can create a total interest-cost gap of approximately VND 800 million to VND 1.5 billion over the full 25-year term. Investors should ask all 3 banks to provide an illustrative calculation of the total interest payable over the entire term before signing the agreement, thereby making a direct comparison and choosing the bank with the lowest actual total cost for their specific profile.
Market rates rise to 12–14% per year — how much can Hồng Hạc City’s preferential rate save investors?
In 5/2026, the average rate for conventional commercial home loans in the Vietnamese market rose sharply to 12–14% per year during the floating-rate period. If an investor borrowed VND 14 billion at 12% per year for an 18-month grace period instead of 0%, the total interest payable would be VND 14,000,000,000 × 12% × 1.5 = VND 2,520,000,000. Accordingly, Hồng Hạc City’s 0% mechanism saves more than VND 2.5 billion during the grace period alone — equivalent to approximately 12% of the value of a standard townhouse. This is a financial advantage unavailable at most conventional commercial property projects currently on the Bắc Ninh market.